FFC vs EFERT vs Fatima: Best Fertilizer Stock 2026
As of 29 October 2026, Fauji Fertilizer (FFC) scores best of the three fertilizer stocks: 8.8 times trailing earnings, an 8.9% dividend yield and net cash. Fatima Fertilizer is cheapest at 6.8 times earnings but has paid little in dividends, while Engro Fertilizers (EFERT) earns the highest return on equity but carries the most debt.
Key takeaways
- FFC scores best overall: a P/E of 8.8, an 8.9% dividend yield, a 34% ROE and more cash than debt.
- Fatima is cheapest at 6.8 times earnings and 1.6 times book value, but it declared no dividend in 2026, so its yield is only 1.8%.
- Engro Fertilizers grew nine-month EPS fastest (+13.8%) and has a 49% ROE, but it trades at 10.4 times earnings and has net debt of about 1.6 times its equity.
- Fatima's core business grew strongly (gross profit +21.8%), but a 64% fall in other income held nine-month profit growth to 3.6%.
- FFC sold 2,160 thousand tonnes of urea in nine months, about 49% of Pakistan's market; Engro's urea sales fell about 4% before rebounding in the third quarter.
PSX retail investor
M Zubair is a retail investor on the Pakistan Stock Exchange. He writes SeekhKar's guides to explain the basics of investing, such as reading annual reports, P/E ratios, dividends and valuation, in simple language for new PSX investors. Everything here is for learning, not investment advice.
FFC vs EFERT vs Fatima: Valuation at a Glance
Fauji Fertilizer Company (FFC), Engro Fertilizers (EFERT) and Fatima Fertilizer Company (FATIMA) are the three urea makers in the KSE-100 index. All three use the calendar year as their financial year, so their results for the nine months to 30 September 2026 (9M 2026) cover the same period. Prices are PSX closing prices on 29 October 2026.
Earnings are trailing twelve months (TTM): 9M 2026 plus the fourth quarter of 2025. Dividends are those declared over the same period: the final dividend for 2025 plus the 2026 interim dividends.
| Metric | FFC | Engro Fertilizers (EFERT) | Fatima (FATIMA) |
|---|---|---|---|
| Share price, 29 Oct 2026 | Rs 561.05 | Rs 192.57 | Rs 138.93 |
| Market capitalisation | Rs 807 bn | Rs 257 bn | Rs 292 bn |
| EPS, 9M 2026 | Rs 48.77 | Rs 12.17 | Rs 14.27 |
| EPS, TTM | Rs 63.91 | Rs 18.43 | Rs 20.53 |
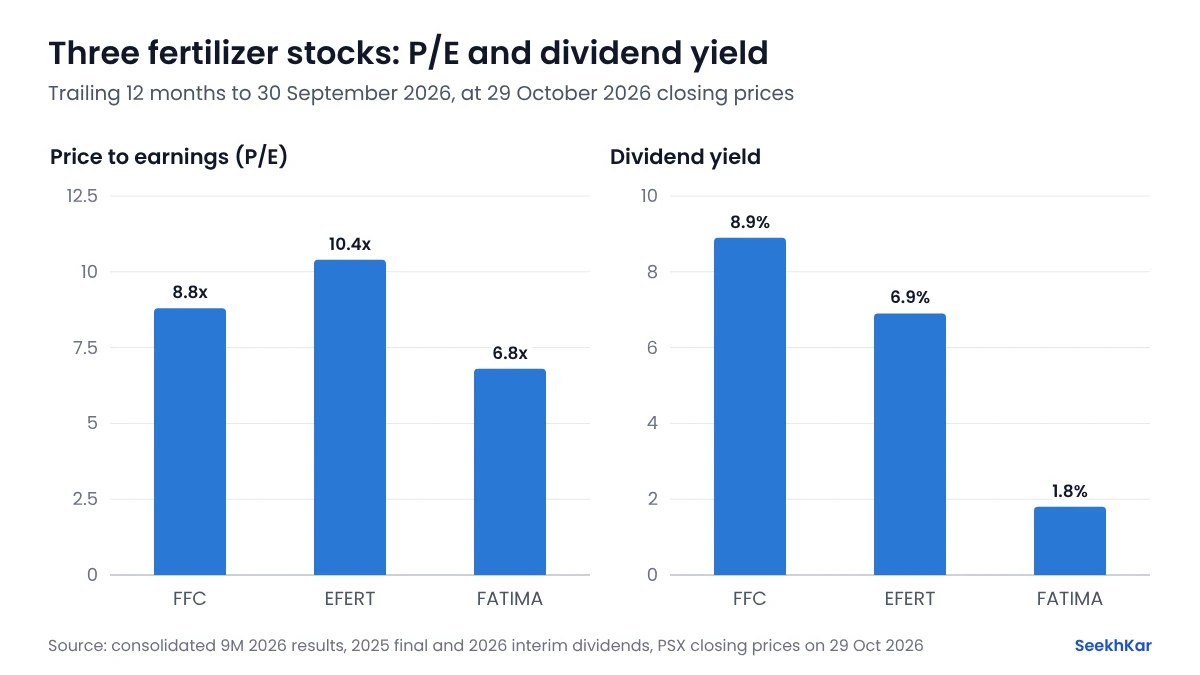
| P/E, TTM | 8.8x | 10.4x | 6.8x |
| Book value per share, latest | Rs 190.32 | Rs 37.91 | Rs 88.12 |
| P/B | 2.95x | 5.08x | 1.58x |
| ROE (TTM EPS ÷ book value) | 33.6% | 48.6% | 23.3% |
| Dividend per share, TTM | Rs 50.00 | Rs 13.25 | Rs 2.50 |
| Dividend yield | 8.9% | 6.9% | 1.8% |
| EPS growth, 9M 2026 vs 9M 2025 | +12.6% | +13.8% | +3.6% |
All earnings are consolidated, so each company is shown with its subsidiaries and associates. Book values are consolidated, from S&P Global data: 30 September 2026 for EFERT and 30 June 2026 for FFC and Fatima. On FFC's own (standalone) accounts, with nine-month EPS of Rs 44.59 and 2026 dividends only, the P/E is 10.1 and the yield 7.4%.
Which Fertilizer Stock Is Cheapest on P/E and P/B?
Fatima is the cheapest on both measures. At Rs 138.93, it trades at 6.8 times trailing earnings and 1.58 times book value. FFC is in the middle at 8.8 times earnings, and Engro Fertilizers is the most expensive at 10.4 times. The average P/E of the three is 8.7.
The P/B gap is wider: EFERT trades at about five times book value and Fatima at about one and a half. That is mostly because of how much each company pays out. EFERT has paid most of its profit as dividends for years, so its equity is small (Rs 37.91 a share) and its return on that equity is high (48.6%). Fatima keeps most of its profit, so its equity is larger and its ROE lower (23.3%). For a company that pays out most of what it earns, P/E is the more useful comparison.
Our fertilizer sector guide gives the sector's typical P/E and P/B ranges and the numbers to check.
Which Company Grew Profit Fastest in 2026?
| Company | Profit after tax, 9M 2026 | 9M 2025 | Change | Q3 2026 EPS | Q3 2025 EPS |
|---|---|---|---|---|---|
| FFC | Rs 71.02 bn | Rs 63.04 bn | +12.7% | Rs 19.72 | Rs 17.24 |
| Engro Fertilizers | Rs 16.24 bn | Rs 14.27 bn | +13.8% | Rs 6.83 | Rs 4.35 |
| Fatima | Rs 29.96 bn | Rs 28.91 bn | +3.6% | Rs 4.53 | Rs 5.70 |
Engro Fertilizers grew fastest, almost all of it in the third quarter. Its Q3 EPS rose 57% as urea sales rose 21% to 711 thousand tonnes and gross margin reached 35%, after a weak first half.
FFC grew steadily on higher urea sales. Its own accounts show other income, mainly from investments, of Rs 37.5 billion in nine months, about 37% of pre-tax profit, so part of its earnings does not come from selling fertilizer.
Fatima's headline growth hides a better core result. Its gross profit rose 21.8% to Rs 78.2 billion and its gross margin widened to 40.2% from 35.9%. But other income fell 63.7% to Rs 4.6 billion, which held profit growth to 3.6%, and its third-quarter EPS fell 21%.
Urea Sales: Who Is Winning Market Share?
FFC filed its own urea figures with its results: it sold 2,160 thousand tonnes in 9M 2026, up 10.5%, in a Pakistan urea market that grew 4.7% to 4,404 thousand tonnes. That is about 49% of the market. Arif Habib Limited estimated that Fatima's urea sales rose about 8% over the same nine months, while Engro Fertilizers' fell about 4%.
The third quarter reversed part of that. In September 2026 alone, Engro sold 218 thousand tonnes, more than double a year earlier, lifting its monthly share to 35% from 24%. FFC's share that month eased to 43% from 55%, and Fatima's rose to 17% from 12%. Urea stocks held by the industry fell to 643 thousand tonnes at the end of September, from a peak of 971 thousand tonnes in May.
All three depend on natural gas, the main raw material for urea. A gas shortage already cut FFC's granular urea output by 15% in 2026, so gas supply and the price the government sets for it are a main risk for all three, along with controls on the urea price.
Which Fertilizer Stock Pays the Highest Dividend?
| Company | Final for 2025 | Declared in 2026 | TTM dividend | Yield | Yield after 15% tax | Payout of TTM EPS |
|---|---|---|---|---|---|---|
| FFC | Rs 8.50 | Rs 41.50 | Rs 50.00 | 8.9% | 7.6% | 78% |
| Engro Fertilizers | Rs 4.00 | Rs 9.25 | Rs 13.25 | 6.9% | 5.8% | 72% |
| Fatima | Rs 2.50 | None | Rs 2.50 | 1.8% | 1.5% | 12% |
FFC pays the most. At 29 October prices, Rs 100,000 invested in FFC would have earned about Rs 7,580 in dividends over the last twelve months after the 15% withholding tax for filers, against about Rs 5,850 from Engro Fertilizers and Rs 1,530 from Fatima.
FFC has raised its dividend every quarter of 2026, to Rs 18.50 for the third. Engro paid Rs 9.25 in 2026, less than the Rs 11 it paid in the first nine months of 2025. Fatima declared no dividend with its second- or third-quarter results; it paid Rs 6 for 2025 in total. Our guide to dividend investing in Pakistan explains how to judge whether a payout can last.
Debt, Cash and Shariah Status
| Company | Net cash (debt) | Equity | Net debt ÷ equity | Balance sheet date |
|---|---|---|---|---|
| FFC | Rs 90.7 bn net cash | Rs 277.4 bn | None | 30 Jun 2026 |
| Fatima | Rs 7.6 bn net debt | Rs 185.1 bn | 0.04x | 30 Jun 2026 |
| Engro Fertilizers | Rs 79.2 bn net debt | Rs 50.6 bn | 1.56x | 30 Sep 2026 |
FFC holds more cash and short-term investments than it owes, which is where much of its other income comes from. Fatima's debt is small next to its equity. Engro Fertilizers' net debt is larger than its equity, which is small because it pays out most of its profit, so a higher interest rate costs it the most. The State Bank of Pakistan raised its policy rate to 12% from 27 October 2026.
On 27 October 2026, FFC (12.45%) and Engro Fertilizers (5.00%) were among the ten largest weights in the KMI-30 Shariah index. Our KMI-30 Shariah investing guide explains how to check any stock's status, including Fatima's.
Scorecard: Which Fertilizer Stock Looks Best Value Today?
We ranked the three companies from 1 (best) to 3 on six measures, with equal weight. A lower total is better.
| Company | P/E | P/B | Dividend yield | ROE | EPS growth | Debt | Total |
|---|---|---|---|---|---|---|---|
| FFC | 2 | 2 | 1 | 2 | 2 | 1 | 10 |
| Engro Fertilizers | 3 | 3 | 2 | 1 | 1 | 3 | 13 |
| Fatima | 1 | 1 | 3 | 3 | 3 | 2 | 13 |
- All-round and income: FFC. The highest yield, net cash and steady growth at 8.8 times earnings. The risks are its reliance on investment income and a 78% payout that leaves little cushion.
- Value: Fatima. The lowest P/E and P/B and a strong core business. The risks are a small dividend and a third quarter in which EPS fell 21%.
- Growth and ROE: Engro Fertilizers. The fastest growth and highest ROE, with a strong third quarter. The risks are the highest P/E and the most debt, which a higher interest rate makes more costly.
Fertilizer makers have steady cash flows, so a discounted cash flow or dividend discount model can work for them if you keep the gas price and payout assumptions realistic. You can test your own assumptions in our intrinsic value calculator.
This comparison is educational and is not a recommendation to buy or sell any stock. Prices change daily, and we update these figures after each quarterly result.
Sources & Further Reading
- FFC: financial results for the quarter ended 30 Sep 2026 (PSX filing, 28 Oct 2026)
- Engro Fertilizers: nine-month results and Rs5.50 interim dividend (PSX filing, 19 Oct 2026)
- Fatima Fertilizer: results for the quarter ended 30 Sep 2026 (PSX filing, 29 Oct 2026)
- Trade Chronicle: Pakistan fertilizer sector 3QCY26 snapshot (AHL Research)