UBL vs Meezan vs HBL vs MCB: Best Bank Stock 2026
As of 28 October 2026, HBL is the cheapest of the four big banks at 6.1 times trailing earnings and 0.87 times book value, while UBL combines the fastest profit growth (+15.8% in 9M 2026) with a P/E of 7.0. MCB pays the highest dividend yield (9.2%) and Meezan has the highest ROE but the richest valuation.
Key takeaways
- HBL is the cheapest of the four at 6.1 times trailing earnings and 0.87 times book value, the only one priced below its net assets.
- UBL grew earnings per share 15.8% in 9M 2026, the fastest of the group, but part of that came from about Rs 48 billion of gains on securities.
- MCB has the highest dividend yield at 9.2% (about 7.9% after the 15% filer tax), but its profit was flat and it pays out 73% of earnings.
- Meezan Bank has the highest ROE (32.4%) and is the only Shariah-compliant stock of the four, but it trades at the highest multiples: 9.9x earnings and 3.2x book.
- The State Bank of Pakistan raised the policy rate to 12% from 27 October 2026, so the 9M 2026 results in this comparison were earned before that change.
PSX retail investor
M Zubair is a retail investor on the Pakistan Stock Exchange. He writes SeekhKar's guides to explain the basics of investing, such as reading annual reports, P/E ratios, dividends and valuation, in simple language for new PSX investors. Everything here is for learning, not investment advice.
UBL vs Meezan vs HBL vs MCB: Valuation at a Glance
United Bank Limited (UBL), Meezan Bank Limited (MEBL), Habib Bank Limited (HBL) and MCB Bank Limited (MCB) are four of the largest banks in the KSE-100 index. The figures below use the results each bank filed with the PSX for the nine months to 30 September 2026 (9M 2026) and closing prices on 28 October 2026.
Earnings and dividends are trailing twelve months (TTM): 9M 2026 plus the fourth quarter of 2025. That puts all four banks on the same October 2025 to September 2026 period, so the ratios are directly comparable.
| Metric | UBL | Meezan (MEBL) | HBL | MCB |
|---|---|---|---|---|
| Share price, 28 Oct 2026 | Rs 410.36 | Rs 523.76 | Rs 287.66 | Rs 389.32 |
| Market capitalisation | Rs 1,028 bn | Rs 946 bn | Rs 422 bn | Rs 461 bn |
| EPS, TTM | Rs 58.49 | Rs 52.90 | Rs 47.35 | Rs 49.13 |
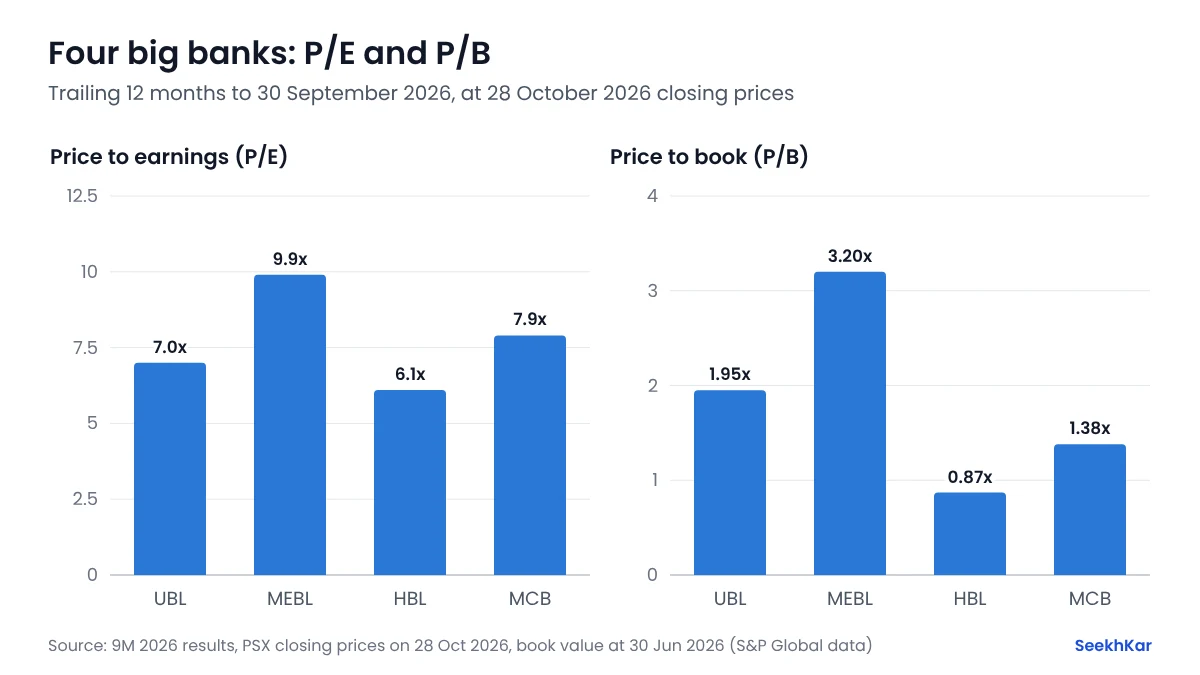
| P/E, TTM | 7.0x | 9.9x | 6.1x | 7.9x |
| Book value per share, 30 Jun 2026 | Rs 210.58 | Rs 163.44 | Rs 329.98 | Rs 282.03 |
| P/B | 1.95x | 3.20x | 0.87x | 1.38x |
| ROE (TTM EPS ÷ book value) | 27.8% | 32.4% | 14.3% | 17.4% |
| Dividend per share, TTM | Rs 32.00 | Rs 30.50 | Rs 24.00 | Rs 36.00 |
| Dividend yield | 7.8% | 5.8% | 8.3% | 9.2% |
| EPS growth, 9M 2026 vs 9M 2025 | +15.8% | +6.3% | +5.3% | −0.4% |
All earnings are consolidated. Book values are from S&P Global data for 30 June 2026, the latest balance sheet available for all four banks. Our ROE uses total equity, so it can differ from the ROE each bank reports: Meezan reported 34.7% for the first half of 2026, and MCB reported 22.2% on a standalone basis for 9M 2026.
Which Bank Stock Is Cheapest on P/E and P/B?
HBL is the cheapest on both measures. At Rs 287.66, each HBL share buys Rs 47.35 of yearly earnings (6.1x) and Rs 329.98 of book value (0.87x), so the market values HBL below its net assets. Meezan is the most expensive at 9.9x earnings and 3.2x book. The average P/E of the four is 7.7x: UBL (7.0x) sits just below it and MCB (7.9x) just above.
A low P/B is not automatically a bargain. A bank that earns 30% a year on its equity deserves a higher multiple of book value than one that earns 15%. That is why Meezan, with a 32.4% ROE, trades at 3.2x book while HBL, with 14.3%, trades below book. For a bank, P/B divided by ROE equals the P/E, so the P/E already captures this trade-off; on that basis HBL is still the cheapest and Meezan the most expensive.
To see how these multiples compare with other industries, read our guide to P/E ratios by sector in Pakistan.
Which Bank Has the Strongest Profit Growth and ROE?
| Bank | Profit after tax, 9M 2026 | 9M 2025 | Change |
|---|---|---|---|
| UBL | Rs 116.56 bn | Rs 100.09 bn | +16.5% |
| Meezan Bank | Rs 74.65 bn | Rs 70.52 bn | +5.9% |
| HBL | Rs 54.11 bn | Rs 51.38 bn | +5.3% |
| MCB | Rs 44.33 bn | Rs 44.63 bn | −0.7% |
UBL grew fastest, but check what drove it. Its non-interest income more than doubled (+107%) to Rs 98.1 billion, helped by about Rs 48 billion of gains on securities. In the third quarter, costs rose to 46% of income and quarterly EPS fell 13% to Rs 12.24. Gains from selling bonds do not recur every year, so part of UBL's 2026 growth may not carry into 2027.
Meezan has the highest ROE at 32.4% on our measure, and its third-quarter profit rose 11% to Rs 26.01 billion. HBL posted a record quarterly profit of Rs 19.58 billion in Q3 2026, up 16%, but its ROE of 14.3% is the lowest of the four, partly because of a higher cost base: its cost-to-income ratio was 55.6% in 2025, against 38.6% at MCB in 9M 2026. MCB's profit was flat, although its deposits grew 22% to Rs 2.71 trillion.
Which Bank Pays the Highest Dividend?
| Bank | Declared, 9M 2026 | Final for 2025 | TTM dividend | Yield | Yield after 15% tax | Payout ratio |
|---|---|---|---|---|---|---|
| MCB | Rs 27.00 | Rs 9.00 | Rs 36.00 | 9.2% | 7.9% | 73% |
| HBL | Rs 18.00 | Rs 6.00 | Rs 24.00 | 8.3% | 7.1% | 51% |
| UBL | Rs 24.00 | Rs 8.00 | Rs 32.00 | 7.8% | 6.6% | 55% |
| Meezan Bank | Rs 23.50 | Rs 7.00 | Rs 30.50 | 5.8% | 4.9% | 58% |
MCB pays the most. At these yields, Rs 100,000 invested in MCB would have earned about Rs 7,860 in dividends over the last twelve months after the 15% withholding tax for filers, against about Rs 4,950 from Meezan. Non-filers pay 30%, which roughly halves the gain from these yields.
MCB has paid Rs 9 per share every quarter, but it already pays out 73% of earnings, so with flat profit there is little room to raise the dividend. UBL and HBL pay out about half their earnings, which leaves more room to grow payouts. Our guide to dividend investing in Pakistan explains how to compare yields after tax.
Meezan vs UBL, HBL and MCB: The Shariah Question
Meezan Bank is the only fully Islamic bank of the four, so it is the only one of these stocks that a Shariah-compliant investor can hold. UBL, HBL and MCB are conventional banks: they run Islamic banking windows, but most of their income is interest, so their shares do not pass Shariah screening.
Part of Meezan's premium valuation likely reflects this, alongside its higher ROE. If you only invest in Shariah-compliant stocks, compare Meezan with other Islamic banks rather than with these three. Our KMI-30 Shariah investing guide explains how screening works.
What Does the October 2026 Rate Hike Mean for These Banks?
On 26 October 2026 the State Bank of Pakistan raised its policy rate by 50 basis points to 12%, effective 27 October. All the results above were earned before this change, so its effect will show in Q4 2026 and 2027 figures.
Pakistani banks hold large portfolios of government securities, so a higher policy rate tends to lift their interest income as those securities reprice. It also raises what they pay on savings deposits. Banks funded more by current accounts, which pay no profit, tend to gain the most. MCB's current accounts were 56% of its deposits in March 2026, while HBL's domestic current-account mix was 38.6% at the same date.
Scorecard: Which Bank Stock Looks Best Value Today?
We ranked the four banks from 1 (best) to 4 on five measures, with equal weight. A lower total is better.
| Bank | P/E | P/B | Dividend yield | ROE | EPS growth | Total |
|---|---|---|---|---|---|---|
| UBL | 2 | 3 | 3 | 2 | 1 | 11 |
| HBL | 1 | 1 | 2 | 4 | 3 | 11 |
| MCB | 3 | 2 | 1 | 3 | 4 | 13 |
| Meezan Bank | 4 | 4 | 4 | 1 | 2 | 15 |
UBL and HBL tie, and the better choice depends on what you want from a bank stock:
- Value: HBL has the lowest P/E and is the only one trading below book value. The risk is its low ROE and high cost base.
- Growth at a fair price: UBL has the fastest earnings growth and a 27.8% ROE at 7.0x earnings. The risk is that some of that growth came from one-off securities gains.
- Income: MCB has the highest dividend yield. The risk is flat earnings and a 73% payout ratio.
- Shariah compliance and quality: Meezan has the highest ROE. The risk is that it is the most expensive on every multiple.
Why we did not use DCF. For a bank, deposits and loans are raw material rather than financing, so free cash flow is not a meaningful measure and a standard DCF does not work. Banks are valued instead on P/E, P/B against ROE, and dividend discount models. To estimate a dividend-based fair value with your own assumptions, use our intrinsic value calculator.
This comparison is educational and is not a recommendation to buy or sell any stock. Prices change daily, and we update these figures after each quarterly result.