Pioneer Cement vs Power Cement: Cement Stocks 2026
On 2 November 2026 prices, Pioneer Cement scores slightly better on our scorecard: its Q1 FY27 profit rose 73% and it has almost no debt. Power Cement is a little cheaper, at 6.8 times trailing earnings against 7.1, and earns a higher ROE, but carries more debt. Neither paid a dividend for FY26.
Key takeaways
- Pioneer Cement scores 8 on our six-measure scorecard (lower is better) and Power Cement 9.
- Pioneer's Q1 FY27 profit rose 73% to Rs 2.21 billion as its finance cost fell 94% and its gross margin rose to 34.7%.
- Power Cement's profit rose 31% to Rs 1.05 billion on 36% higher sales.
- Neither company paid a dividend for FY26; Pioneer has approved lending up to Rs 4 billion to Maple Leaf Cement, its holding company.
- Thatta Cement is not included yet: it has until 29 November 2026 to file its Q1 FY27 accounts.
PSX retail investor
M Zubair is a retail investor on the Pakistan Stock Exchange. He writes SeekhKar's guides to explain the basics of investing, such as reading annual reports, P/E ratios, dividends and valuation, in simple language for new PSX investors. Everything here is for learning, not investment advice.
Pioneer vs Power Cement: Valuation at a Glance
Pioneer Cement (PIOC) and Power Cement (POWER) extend our cement coverage after the four largest cement makers and Cherat, Bestway and Kohat. Pioneer is in Punjab and is now controlled by Maple Leaf Cement; Power Cement is in Sindh. Both end their year on 30 June. Prices are PSX closing prices on 2 November 2026.
Earnings are trailing twelve months (TTM): FY26 EPS, minus Q1 FY26, plus Q1 FY27.
| Metric | PIOC | POWER |
|---|---|---|
| Share price, 2 Nov 2026 | Rs 235.63 | Rs 21.33 |
| Market capitalisation | Rs 54 bn | Rs 28 bn |
| EPS, Q1 FY27 | Rs 9.72 | Rs 0.80 |
| EPS, TTM | Rs 33.14 | Rs 3.13 |
| P/E, TTM | 7.1x | 6.8x |
| Book value per share, 30 Jun 2026 | Rs 218.11 | Rs 18.47 |
| P/B | 1.08x | 1.15x |
| ROE (TTM EPS ÷ book value) | 15.2% | 16.9% |
| Dividend per share, FY26 | None | None |
| Dividend yield | 0% | 0% |
| EPS growth, Q1 FY27 vs Q1 FY26 | +73.3% | +33.3% |
| Net debt ÷ equity, 30 Jun 2026 | −0.04x | 0.64x |
Book values, debt and cash are from S&P Global data. Power Cement's EPS is basic; it also has preference shares that convert into ordinary shares, and its diluted Q1 FY27 EPS was Rs 0.76. A negative net debt figure means more cash than debt.
Which Cement Stock Is Cheaper?
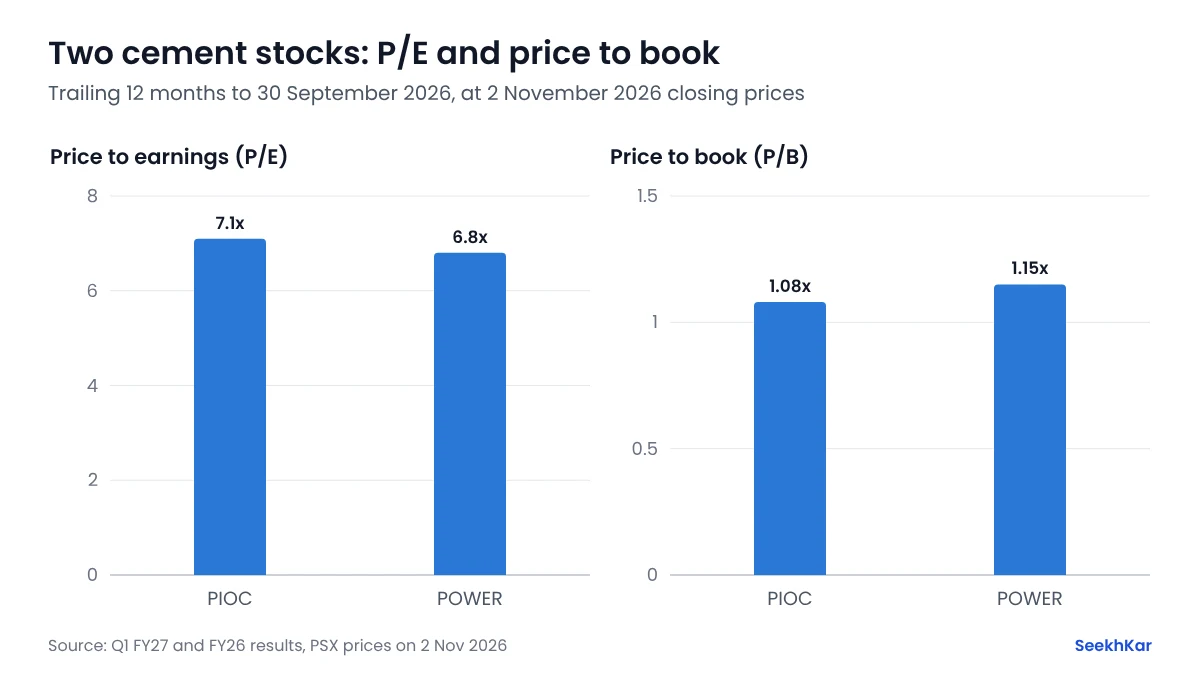
Almost the same price. Power Cement trades at 6.8 times trailing earnings and Pioneer at 7.1; on book value Pioneer is slightly cheaper, 1.08 times against 1.15.
The real difference is debt. Pioneer has no borrowings and a little cash, while Power Cement's debt is Rs 16.4 billion, 0.64 times its equity after cash. Our guide to P/E ratios by sector gives the usual range for cement stocks.
Q1 FY27 Results
| Quarter ended 30 Sep | Net sales, 2026 | 2025 | Profit after tax, 2026 | 2025 | Change |
|---|---|---|---|---|---|
| Pioneer Cement | Rs 10.85 bn | Rs 8.42 bn | Rs 2.21 bn | Rs 1.27 bn | +73% |
| Power Cement | Rs 10.65 bn | Rs 7.81 bn | Rs 1.05 bn | Rs 0.80 bn | +31% |
- Pioneer: sales rose 29% and gross profit 50% to Rs 3.76 billion, a gross margin of 34.7% against 29.8%. Finance cost fell 94% to Rs 14 million. On 3 November it reported finishing a 31 MW solar plant that it says will meet 45% of its energy needs.
- Power Cement: sales rose 36% and gross profit 32% to Rs 3.58 billion, and finance cost fell 19% to Rs 417 million.
Dividends and Debt
Neither company paid a dividend for FY26. Pioneer paid Rs 5 twice for FY25 (March and October 2025), but its board recommended no dividend for FY26, even with a record Rs 6.59 billion profit. Instead it approved loans or advances of up to Rs 4 billion to Maple Leaf Cement, its holding company, for a year from 18 September 2026, at the higher of three-month KIBOR plus 1% or its own borrowing cost.
Power Cement shows no recent cash dividend. Investors who want income from cement stocks will find it in our other comparisons: Bestway, for example, paid Rs 40 a share for FY26. The dividend calculator works out any payout after tax.
Scorecard: Which Cement Stock?
We ranked the two companies 1 (best) or 2 on six measures, with equal weight. Neither pays a dividend, so both rank 1 on yield. A lower total is better.
| Company | P/E | P/B | Dividend yield | ROE | EPS growth | Debt | Total |
|---|---|---|---|---|---|---|---|
| Pioneer Cement | 2 | 1 | 1 | 2 | 1 | 1 | 8 |
| Power Cement | 1 | 2 | 1 | 1 | 2 | 2 | 9 |
- Growth with no debt: Pioneer Cement. 73% profit growth and a clean balance sheet. The risks are no dividend and money lent to its parent.
- Slightly cheaper, more debt: Power Cement. The lower P/E and higher ROE. The risks are its debt and no dividend.
Our cement sector guide lists the other numbers to check, such as dispatches, coal costs and capacity. We will add Thatta Cement when it files its Q1 FY27 accounts. This comparison is educational and is not a recommendation to buy or sell any stock. Prices change daily, and we update these figures after each quarterly result.